
SpaceX is looking for another mountain of capital for AI
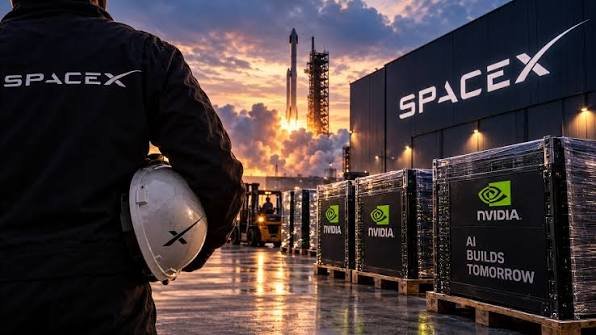
SpaceX is in talks with banks and major asset managers to raise approximately $40 billion to finance large purchases of AI chips from NVIDIA.
The story was first reported by the Financial Times and subsequently covered by Reuters and Bloomberg, although Reuters stressed that the financing has not been finalized.
The reported structure would include:
- $10 billion in bank loans;
- $30 billion in investment-grade debt;
- Apollo Global Management expected to lead the transaction;
- PIMCO among investors discussing the financing.
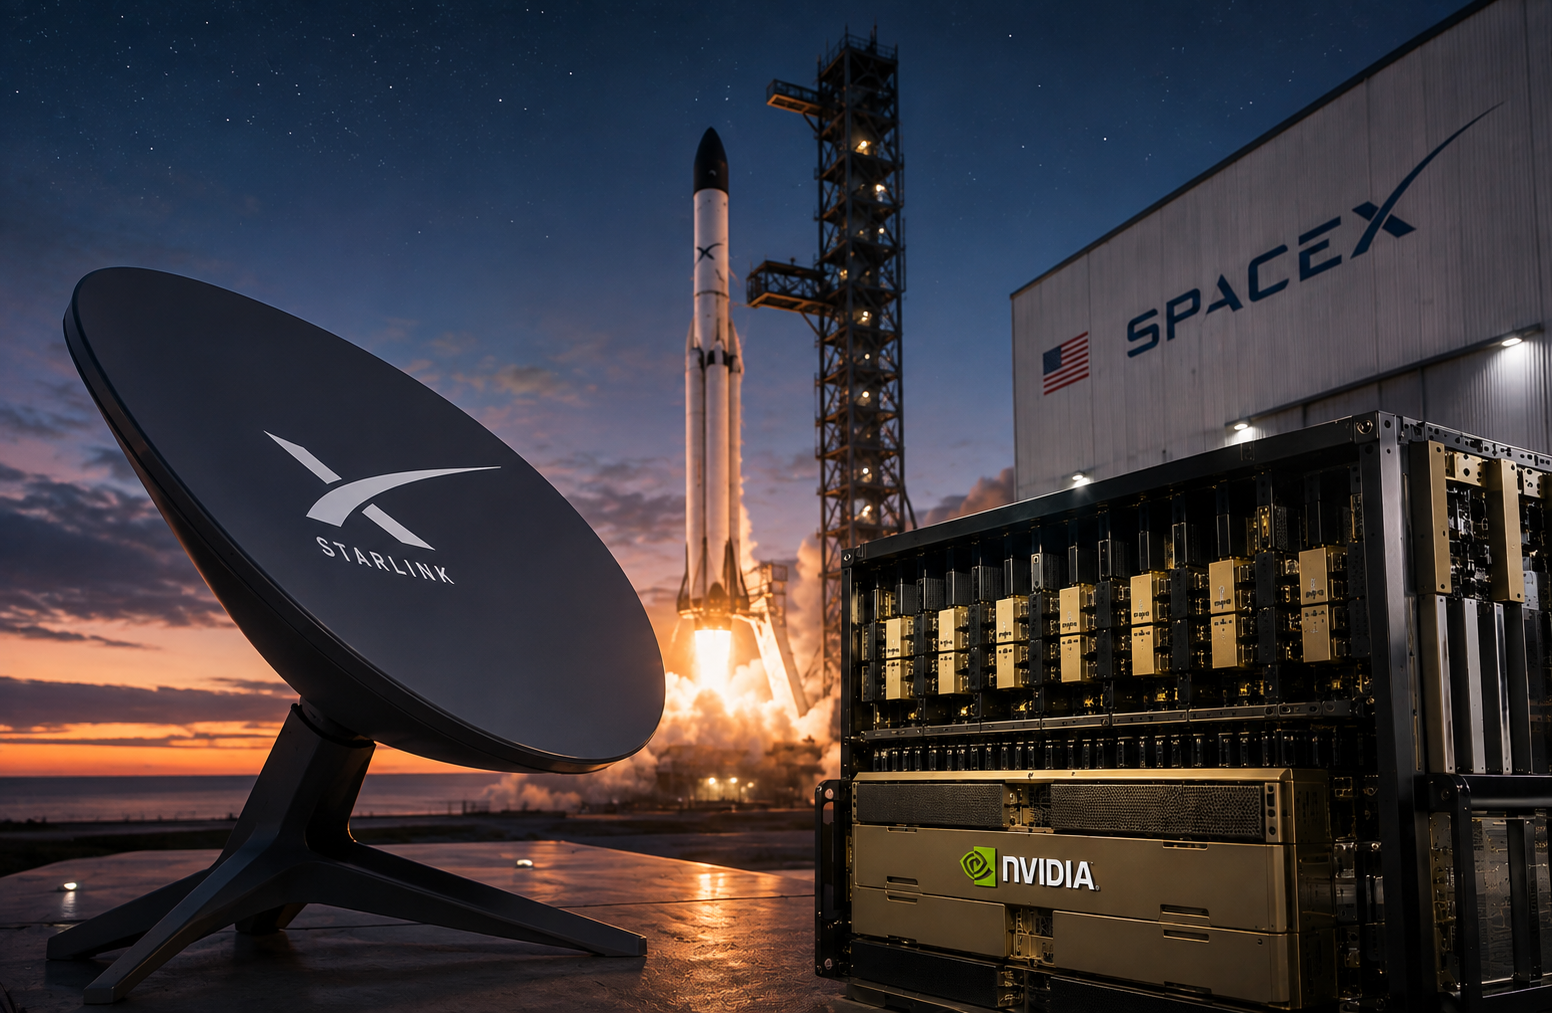
Why does SpaceX need so much compute?
This story is not really about rockets.
SpaceX is increasingly expanding into AI infrastructure, through data centers associated with Elon Musk’s broader AI ecosystem.
A major component is Colossus, the computing infrastructure used for AI workloads and associated with the development of Grok.
SpaceX is also developing a model in which computing capacity can be rented to outside customers. Reporting has linked major AI companies, including Anthropic and Google, to agreements involving compute capacity.
That changes the economics of the investment.
SpaceX is not simply buying GPUs for internal use. It is attempting to build a large computing asset that can generate revenue by selling compute capacity to others.
NVIDIA sits at the center of the bet
The reported plan is centered on NVIDIA’s AI processors, which remain dominant across advanced AI training and inference infrastructure.
The Financial Times reported that SpaceX plans to use NVIDIA chips exclusively in its AI data centers, while Musk has backed NVIDIA’s new Vera Rubin architecture.
That creates a powerful chain:
SpaceX → buys compute
NVIDIA → supplies the hardware
AI companies → rent or purchase compute
Investors → finance the expansion
It is becoming one of the defining structures of the AI economy.
$40 billion is not an ordinary investment
The size matters partly because much of the funding would come through debt.
SpaceX has already entered public capital markets and completed a major bond sale. The Financial Times reported that the company has an investment-grade BBB rating, while investors have raised concerns about very high capital spending and relatively limited financial disclosure.
The central question therefore is not simply:
“Can SpaceX buy the GPUs?”
It is:
“Can the GPUs generate enough revenue to justify the debt?”
GPUs are becoming financial assets
Something larger is happening across the industry.
Advanced GPUs are no longer viewed merely as electronic components.
They are increasingly being treated as financeable assets, because they produce computing capacity that can be sold to customers.
NVIDIA itself has become involved in broader financing efforts aimed at supporting hundreds of billions of dollars of AI infrastructure investment.
That creates questions more familiar from aircraft, telecom or energy financing:
How long does a GPU remain economically productive?
And:
How much revenue can a specific chip generation generate before newer hardware makes it less competitive?
The risk: AI hardware ages quickly
Debt financing creates a major technological risk.
A data center built today may deploy cutting-edge GPUs.
A few years later, a much more efficient architecture could arrive.
That creates a financial challenge.
If a company takes on long-term debt to purchase today’s GPUs, those chips must continue producing revenue even as new generations appear.
Reuters has reported that some lenders and investors have become more cautious about treating AI chips as long-term collateral.
SpaceX is not alone
The development comes as virtually every major technology company faces the same problem:
AI requires more compute.
Amazon has reportedly considered a structure involving roughly $8 billion of NVIDIA chips, while other companies are increasingly linking AI infrastructure spending to debt, private capital and long-term customer contracts.
The competitive question is therefore shifting from:
“Who has the best model?”
to:
“Who can finance and deploy compute fastest?”
From 1.4 GW toward a much larger AI footprint
Reuters Breakingviews reported that SpaceX aims to increase its computing capacity from roughly 1.4 GW to 15 GW by the end of 2027, if the reported plans materialize.
That scale pushes AI infrastructure closer to the economics of the power industry.
A large data center requires:
- GPUs;
- electricity;
- transformers;
- cooling;
- networking;
- fiber;
- buildings;
- backup systems;
- maintenance;
- financing.
A massive GPU order is therefore only one part of the equation.
What does this mean for the industry?
If the deal goes ahead, it would be a powerful signal that demand for AI compute is expanding beyond traditional AI labs.
For NVIDIA, a purchase of this scale would further reinforce its role as a leading supplier of AI infrastructure.
For SpaceX, success would depend on turning computing capacity into:
AI services → customers → revenue → debt repayment.
If demand remains strong, the model could be highly profitable.
If demand slows or compute prices fall rapidly, the debt burden becomes much more significant.
What you need to know
- SpaceX is in talks to raise roughly $40 billion to finance purchases of NVIDIA AI chips.
- The reported structure includes around $10 billion in bank loans and $30 billion in investment-grade debt.
- Apollo Global Management is expected to lead the financing, while PIMCO is among the investors discussing participation.
- The talks are still at an early stage and could end without a completed transaction.
- The goal is to massively expand computing capacity for AI and SpaceX’s compute-leasing business.
- The move highlights how the AI race is increasingly becoming a race for capital, electricity, GPUs and data centers, not just better models.
What does it mean for users?
There will be no immediate consumer-facing change.
Over time, however, additional compute capacity could influence:
- AI service performance;
- the size of available models;
- API pricing;
- cloud AI services;
- applications built on advanced models.
At the same time, massive data-center expansion could increase pressure on electricity markets, grids and semiconductor supply.
That connects the story to one of the biggest AI infrastructure problems of 2026:
Having a powerful model is not enough. You also need the energy and hardware to run it.
What happens next?
The most important point is that the $40 billion financing is not yet a completed deal.
Bloomberg reported that the talks are still at an early stage and could end without a transaction.
If the deal advances, markets will watch:
- the final debt size;
- financing terms and interest costs;
- the number and type of NVIDIA chips purchased;
- data-center construction speed;
- customer contracts for compute capacity;
- how quickly SpaceX can turn compute into revenue.
Those factors will determine whether this becomes one of the smartest infrastructure bets of the AI era — or an example of the risks involved in financing rapidly changing technology with large amounts of debt.
SpaceX is increasingly moving into a field that once seemed far outside its core identity.
From rockets and satellites to GPUs, data centers and AI compute.
A potential $40 billion financing for NVIDIA chips would rank among the largest AI infrastructure financing efforts, but it should currently be treated as an ongoing negotiation, not a completed transaction.
If it goes ahead, the market message will be clear:
The AI race is entering a phase where capital, electricity and compute are becoming just as strategic as the models themselves.